Actual Cash Value Basics
Gear claims often hinge on two payment methods: Actual Cash Value (ACV) and Replacement Cost (RC). ACV typically subtracts depreciation from the item’s current value, while RC aims to pay the cost to replace the item with like kind and quality, subject to policy terms. The difference matters most for older equipment, where depreciation can reduce the payout even when the gear is still functional.
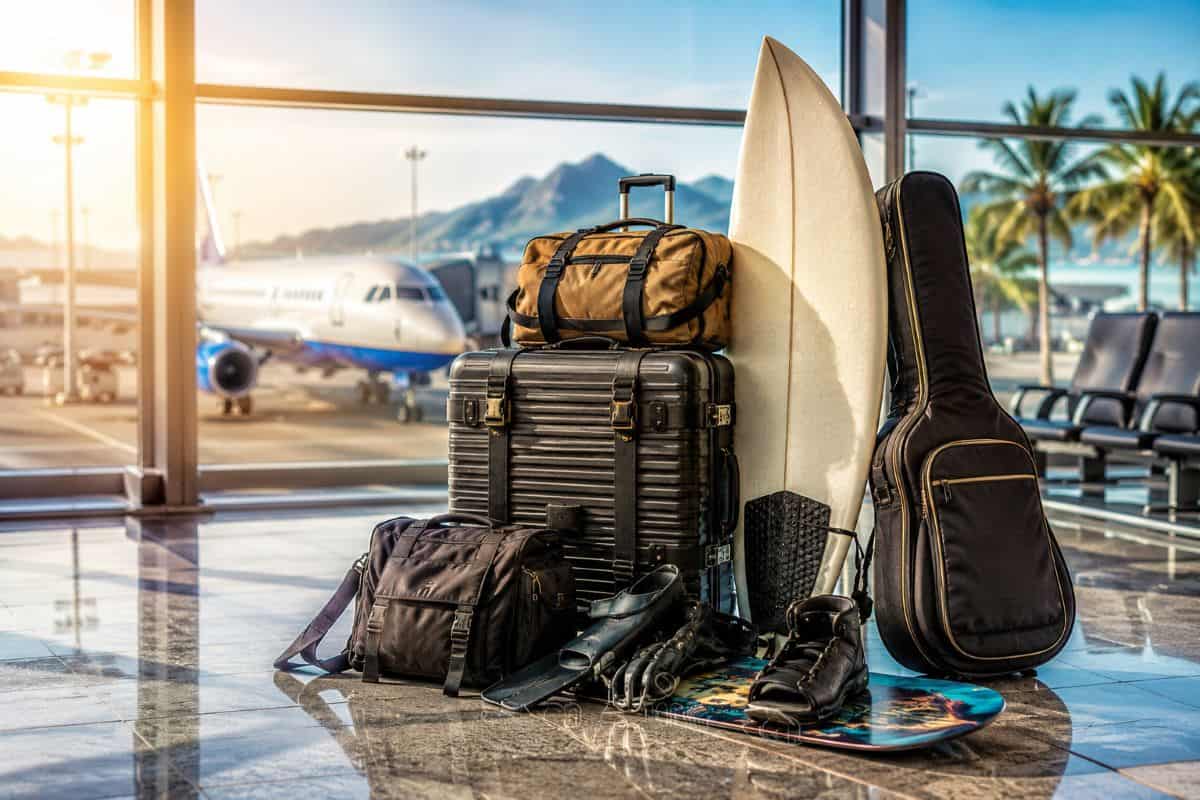
In travel contexts, “gear” can include cameras, laptops, sports equipment, musical instruments, and sometimes clothing or accessories if the policy lists them. Policies may also split coverage into categories such as personal property, scheduled items, or special endorsements for high-value equipment. A claim can be denied or reduced if the policy excludes the item type, the location, or the cause of loss.
For example, a 4-year-old action camera stolen from a hotel room may be paid at ACV under a basic personal property policy. If the same policy offers replacement cost coverage, the insurer may pay RC only after you show proof that you replaced the camera, or it may pay an initial ACV amount and then issue a supplement later. That “supplement later” step is where many claims get delayed, which is annoying when you’re trying to travel again soon.
Where Claims Go Wrong
People often assume that “insurance pays what it costs today.” Many policies instead pay ACV first, then offer RC only under specific conditions. Another common mistake is treating the claim estimate as the final number; insurers may issue an initial payment based on available documentation, then adjust after they verify ownership, condition, and comparable pricing.
Depreciation is the main dependency behind ACV. Insurers estimate depreciation using age, condition, and sometimes a published depreciation schedule or market data. Two items that look similar can receive different depreciation if one has visible wear, missing parts, or a different model year. If you keep receipts, serial numbers, and photos, you reduce the guesswork that drives lower ACV offers.
Supporting technologies also affect outcomes. Many insurers use valuation databases and pricing tools to estimate replacement costs for “like kind and quality.” If your item is discontinued, the insurer may use comparable models, which can lead to a payout that feels mismatched. Some policies require you to provide a replacement quote from a retailer, while others accept online listings; the acceptable sources vary by insurer and policy form.
Coverage details can also depend on claim timing and location. A policy might cover theft in a vehicle only if the item was not visible, or it might exclude theft from unattended vehicles. Travel policies may treat cruise ships, short-term rentals, and hotels differently. The same loss can be handled under different policy sections depending on where it occurred, and that distinction rarely appears in the first email you receive after filing.
How To Choose ACV Or RC
Read The Policy Payment Clause
Start with the exact wording that describes ACV and replacement cost. Look for phrases such as “depreciation,” “actual cash value,” “replacement cost,” and “like kind and quality.” The clause often states whether RC is paid immediately or only after repair or replacement. If the policy says “RC applies only if you replace,” plan for a second step and keep documentation for that step.
Some policies define ACV as replacement cost minus depreciation, while others define it using market value. Those definitions change the math. If you see a reference to a depreciation schedule, note whether it uses age alone or condition too. I’ve seen policies where the schedule assumes “average condition,” which is a problem if your gear was unusually worn or unusually well maintained.
Document Condition And Ownership
For ACV, insurers need enough evidence to estimate depreciation and current condition. For RC, they also need proof that replacement occurred or will occur. Practical documentation includes purchase receipts, credit card statements, serial numbers, model numbers, and dated photos showing the item’s condition before the loss.
For travel gear, a simple workflow helps: store receipts in a cloud folder, photograph serial numbers, and keep a short inventory list with purchase dates. If you use tools like Microsoft OneDrive or Google Photos, label folders by year and category so you can find them quickly during a claim. A dated photo from 2024-03-18 of a camera’s accessories can matter when the insurer asks what was included.
When the insurer requests an itemized list, include accessories that are covered under the policy. If a policy covers only the main device, claiming the full kit can trigger delays or partial denials. If you’re unsure, ask the insurer to confirm what’s covered before you submit a claim supplement.
Estimate Payouts With Realistic Comparables
To compare ACV and RC outcomes, estimate replacement cost using current retail prices for the closest comparable model. Then estimate depreciation using the policy’s method or a conservative assumption based on age and condition. Many people underestimate how much depreciation can reduce ACV for older electronics.
Example approach: if a camera originally cost $900, a policy might depreciate it by a percentage per year or by a schedule tied to age. If depreciation totals 50%, ACV might land near $450 before deductibles and limits. RC might pay closer to today’s replacement price, but only up to policy limits and subject to proof of replacement. The deductible applies in both cases unless the policy states otherwise.
Insurers often require “like kind and quality,” which can mean a comparable feature set rather than the exact same brand or model. If your item is discontinued, the replacement cost may reflect a newer model with different specs, and the insurer may treat that as comparable. That’s where you may need to challenge the comparable if it’s clearly not equivalent.
Plan For RC Supplements And Timelines
Replacement cost coverage frequently includes a two-step process. The insurer pays an initial amount based on ACV, then issues a supplement after you repair or replace the item. The policy may set a deadline for replacement, such as within a certain number of days after the loss. If you miss that deadline, the insurer may stop at ACV.
Keep receipts for the replacement and any repair invoices. If you replace with a different brand, keep documentation showing why it matches “like kind and quality.” Some insurers accept store receipts; others require proof of payment and item details. If you’re traveling, consider whether you can realistically replace the item before the policy deadline, because shipping delays can turn a simple purchase into a paperwork problem.
Also watch for limits. Policies may cap replacement cost for certain categories, require scheduling for high-value items, or exclude collectibles. If your gear exceeds the policy’s general personal property limits, RC may not apply without a specific endorsement.
Case Examples For Travelers
Example 1: Stolen camera with ACV-first payout. A traveler files a claim after a hotel theft of a 3-year-old mirrorless camera. The policy lists personal property with ACV payment and offers replacement cost only for items “replaced within the required time.” The insurer requests proof of ownership and serial number photos. After review, it issues an ACV payment based on depreciation and the camera’s condition, then asks for replacement receipts to release the RC supplement. The traveler receives the supplement 3–4 weeks later after submitting a retailer invoice.
Example 2: Damaged laptop with RC after repair. A renter reports a laptop damaged during a short-term rental stay. The policy covers accidental damage to personal property and states that replacement cost applies if the item is repaired or replaced. The insurer approves a repair estimate from a local service provider and pays for the repair. If the repair is not feasible, the policy shifts to replacement cost, but only after the traveler provides proof of replacement. In this scenario, the payout aligns more closely with replacement cost because the item is restored rather than fully depreciated.
ACV Vs RC Comparison Checklist
| Decision Point | ACV Claim Behavior | Replacement Cost Claim Behavior | What To Prepare |
|---|---|---|---|
| Depreciation | Deducts depreciation from value | Pays closer to current replacement price | Photos, serial numbers, condition notes |
| Timing | Often paid after verification | May require replacement/repair proof | Receipts, repair invoices, replacement deadlines |
| Comparable Items | Uses current value of similar gear | Uses like kind and quality | Retail listings, model specs, included accessories |
| Deductibles And Limits | Deductible reduces payout | Deductible and caps still apply | Policy declarations page, category limits |
Step-by-step checklist before you file:
- Confirm the policy section that covers the loss type (theft, damage, loss of use) and the location where it happened.
- Find the payment clause for ACV and replacement cost, including whether RC requires replacement or repair proof.
- Collect serial numbers, model numbers, purchase dates, and dated photos of condition.
- List included accessories and confirm they match what the policy covers.
- Gather comparable replacement prices from reputable retailers if you plan to challenge the insurer’s estimate.
- Track deadlines for RC supplements and keep replacement receipts in a single folder.
One practical aside: if your insurer’s portal asks for “item description,” copy the exact model name from the device label rather than using a nickname you used while traveling.
Common Mistakes That Reduce Payouts
Submitting a claim without serial numbers or purchase proof often leads to lower ACV estimates or delays. Insurers may still pay, but the lack of documentation increases the chance they treat the item as older or in worse condition. Another frequent issue is claiming accessories that are not covered under the policy’s definition of personal property or scheduled items.
People also miss the deductible and coverage limits. A policy may have a per-item cap or a theft sublimit, so the payout can fall far below what replacement cost suggests. If you have multiple items in one claim, the insurer may apply limits per category, not per receipt.
RC claims fail when replacement proof arrives late. A traveler might buy a replacement after the trip, then discover the policy required replacement within a set number of days. The insurer may then pay only ACV, which feels like a bait-and-switch even when the policy language is clear.
Finally, avoid assuming that “like kind and quality” means identical brand. If the insurer replaces with a materially different spec, you can request reconsideration with comparable listings and a short explanation of why the replacement is not equivalent. That conversation works better when you keep the comparison factual and item-specific.
FAQ
What Does Actual Cash Value Mean?
Actual Cash Value is the insurer’s estimate of what the item is worth at the time of loss, typically after subtracting depreciation for age and condition.
Does Replacement Cost Pay Immediately?
Many policies pay an initial ACV amount first and then pay a replacement-cost supplement after you repair or replace the item and submit proof.
How Do Deductibles Affect ACV And RC?
Deductibles usually reduce the payout under both methods, and policy limits can cap the maximum amount regardless of whether the claim uses ACV or RC.
What Proof Do Insurers Request For Gear?
Common requests include receipts or proof of purchase, serial numbers, model details, photos showing condition, and sometimes a police report for theft.
Can I Challenge The Insurer’s Valuation?
Yes, you can request reconsideration with documented comparable prices and item specifics, but the policy’s definition of “like kind and quality” still governs the outcome.
Author's Insight
ACV and replacement cost differ because they treat depreciation and timing differently. ACV focuses on the item’s estimated worth at the loss date, while replacement cost focuses on the cost to restore the insured property, often after you complete replacement or repair. Policy wording controls whether RC is immediate or conditional, and documentation controls how insurers estimate condition and depreciation.
For travelers, the most practical preparation is an inventory with serial numbers and dated photos, plus a habit of saving receipts in one place. When RC applies, the second-step proof submission matters as much as the initial claim. If you want a cleaner claim process, read the payment clause before a loss and note any deadlines for replacement supplements.
Key Takeaways
- ACV reduces payouts using depreciation; RC aims for replacement pricing but often requires proof of repair or replacement.
- Policy language determines timing, supplements, and whether “like kind and quality” replaces exact models.
- Receipts, serial numbers, and dated photos reduce valuation guesswork and delays.
- Deductibles and category limits can cap both ACV and RC outcomes.
- RC claims commonly fail when replacement proof arrives late, so track deadlines and keep replacement receipts together.